Borrowed Time: The Warning Signs Embedded in Five Thousand Years of Financial Collapse
There is a particular kind of confidence that precedes every debt crisis in the historical record. It is not the confidence of ignorance—most participants in a collapsing credit system are neither stupid nor uninformed. It is the confidence of consensus: the shared, self-reinforcing belief that this time the underlying asset is real, the borrowers are sound, and the expansion is sustainable. Five thousand years of evidence suggests that this confidence is itself the warning sign.
The study of financial crises is, at its core, the study of human psychology applied to scarcity and desire. Modern economists prefer to analyze debt cycles through the lens of interest rates, regulatory frameworks, and institutional design. These are useful tools. But the deeper record—stretching from the clay tablets of ancient Sumer to the collateralized debt obligations of 2007—reveals something that no spreadsheet captures cleanly: the behavioral sequence leading to collapse is nearly identical across every era, every culture, and every asset class.
The Mesopotamian Template
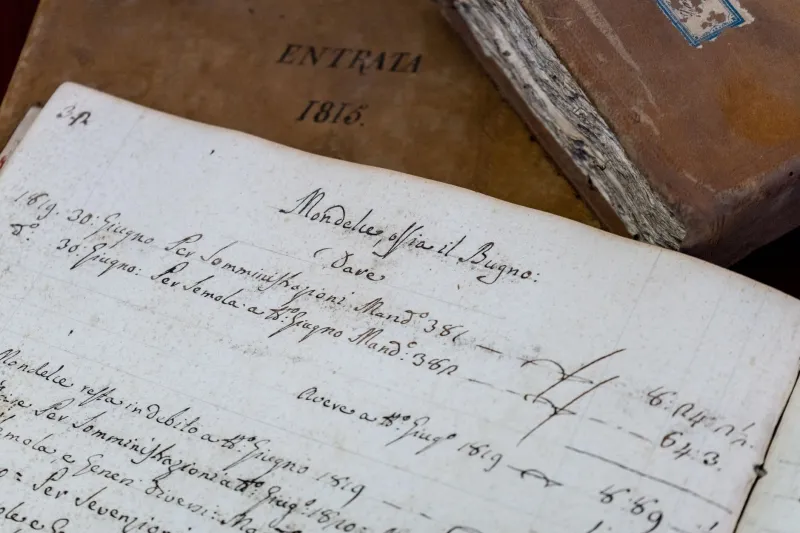
The earliest surviving debt records come from Sumer, circa 3000 BCE. Temple administrators in cities like Uruk and Lagash extended grain and silver loans to farmers, merchants, and craftsmen. The system was sophisticated: interest rates were fixed, contracts were recorded, and enforcement mechanisms existed. It was also prone to catastrophic failure.
When harvests failed or trade routes collapsed, debt obligations cascaded. Farmers who could not repay forfeited land. Landless farmers became dependent laborers. Concentrated land ownership reduced agricultural productivity, which reduced tax revenues, which weakened the state's ability to maintain the infrastructure that made the agricultural system function in the first place. The spiral was self-reinforcing.
Sumerian rulers responded with what they called amargi—a word that translates roughly as "return to the mother" and functioned as a debt jubilee. Periodically, sovereign debts were canceled, enslaved debtors were freed, and land was returned to original holders. Historians have sometimes interpreted this as an act of royal generosity. The more accurate reading is that it was a system reset—a recognition that the debt cycle had reached its terminal phase and that the alternative to cancellation was collapse.
The jubilee did not eliminate the cycle. It reset it. Within a generation, the same dynamics would reassert themselves.
The Structural Sequence
What the historical record reveals, when examined across civilizations and centuries, is not a random series of crises but a recognizable sequence of phases. Credit expands during periods of growth or confidence. Expanded credit enables asset purchases. Rising asset prices validate the credit expansion and encourage further borrowing. New participants enter the market, often with less creditworthiness than earlier borrowers. Standards loosen because the rising asset prices appear to backstop any default risk. Then a triggering event—which is rarely the actual cause of the crisis—exposes the underlying insolvency, and the sequence reverses with compounding speed.
This pattern appears in the Dutch tulip speculation of the 1630s, in the South Sea Bubble of 1720, in the American railroad bond collapses of the 1870s, in the agricultural debt crises of the 1920s that preceded the Great Depression, and in the subprime mortgage expansion of the early 2000s. The assets differ. The mechanics of credit differ. The cultural context differs enormously. The sequence does not.
The Overlooked Indicators
Historians and economists have identified several recurring warning signs that appear consistently in the pre-collapse phase of debt cycles. The first is the democratization of leverage—the moment when access to credit expands beyond its traditional base and reaches populations with limited capacity to absorb losses. In ancient Rome, this appeared as the extension of grain credit to landless citizens who had no collateral. In early twentieth-century America, it appeared as the expansion of installment credit to wage workers. In 2005, it appeared as mortgage products extended to borrowers whose income could not service the debt under any realistic interest rate scenario.
The second warning sign is the abstraction of the underlying asset. When the thing being borrowed against becomes sufficiently complex or distant that lenders can no longer evaluate it directly, the pricing mechanism fails. Medieval European financiers extended credit against future papal tax receipts—instruments so complex that few lenders fully understood the chain of obligation. The collateralized debt obligations of the 2000s were the structural descendants of this same impulse: an asset so abstracted from its underlying reality that its price was maintained by consensus rather than analysis.
The third indicator, and perhaps the most psychologically revealing, is the social stigmatization of skeptics. In every well-documented debt crisis, the historical record shows a period during which those who questioned the asset valuations or credit standards were dismissed, marginalized, or actively ridiculed. This is not incidental. It is functional. The expansion phase of a debt cycle requires broad participation to sustain asset prices, and broad participation requires the suppression of dissent. The moment when questioning the consensus becomes socially costly is precisely the moment when the consensus most needs to be questioned.
Sovereign Debt and the State's Special Problem
Private debt crises are destructive. Sovereign debt crises are civilizationally destabilizing. The historical record on this point is unambiguous.
The Spanish Crown defaulted on its sovereign obligations fourteen times between 1557 and 1696. Each default followed a period in which anticipated revenues from the Americas were pledged against current expenditures, creating a structural gap between obligation and capacity. The creditors—primarily Genoese and German banking houses—continued extending credit because the alternative was to acknowledge losses already on their books. Both parties had incentives to maintain a fiction that neither believed.
This dynamic appears with remarkable consistency in the modern era as well. The Latin American debt crises of the 1980s, the Asian financial crisis of 1997, the Greek sovereign debt crisis of 2010—each followed a period in which international creditors extended loans at favorable rates to sovereigns whose fiscal positions were, on close examination, already untenable. The loans continued because acknowledging the problem would have required acknowledging prior errors. The delay made the eventual reckoning more severe.
What the Record Suggests
The uncomfortable implication of five thousand years of financial history is that debt crises are not anomalies. They are the system operating as designed, or rather, as human psychology designs it. The expansion of credit is rational at the individual level during the growth phase. The reluctance to be the first to exit is rational when asset prices are still rising. The stigmatization of skeptics is rational from the perspective of those whose positions depend on continued confidence. Every step in the sequence is locally rational. The aggregate outcome is catastrophic.
Modern financial regulation attempts to interrupt this sequence through institutional mechanisms: capital requirements, stress tests, leverage limits. These tools have value. But the historical record offers a sobering assessment of their durability. Regulatory frameworks are designed by human beings operating within the same psychological constraints as everyone else. They tend to be designed in response to the last crisis, calibrated to the last asset class, and administered by institutions with their own incentive structures.
The Sumerians had debt jubilees. The Romans had debt relief legislation. The Americans have bankruptcy courts and the Federal Reserve. The cycle continues.
The five-thousand-year record does not suggest that financial crises are inevitable in any specific instance. It suggests that the behavioral conditions that produce them are a stable feature of human psychology, and that recognizing the sequence—credit expansion, asset inflation, standard erosion, skeptic suppression, triggering event, cascade—is the closest thing to a warning system the historical record provides. Whether any given society chooses to act on that warning is a different question entirely, and the record on that point is considerably less encouraging.